Gold prices surged.
China's industrial production index fell to its lowest level since 2012, and a weaker US dollar helped...
China's industrial production index fell to its lowest level since 2012, and a weaker US dollar helped gold prices surge.
Spot gold rose 1% yesterday to $1,128.4. In Asian trading this morning, the price continued to approach the $1,130 mark – the highest level since November 3rd. Similarly, April gold futures also rose 1% to $1,128. SJC gold closed yesterday at 32.84-32.9 million VND per tael.
Thus, precious metals surged to a three-month high after data from China suggested that the economy is unlikely to recover in the short term. China's manufacturing PMI, released yesterday, showed its lowest level since 2012. In addition, economic growth in Europe remains sluggish.
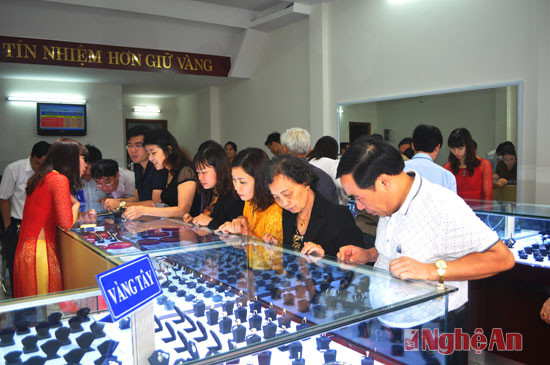 |
| Customers buying gold at the Bac A Gold branch. Photo: Hoang Vinh |
"The disappointing economic data from China, in both the manufacturing and non-manufacturing sectors, partly reveals the volatility in the global economy. In addition, the potential slowdown in economic growth is also contributing to gold prices breaking through the $1,115-$1,120 resistance zone," said Robin Bhar, head of metals research at Socite Generale in London.
The December economic data also suggests that US manufacturing activity is unlikely to recover in the short term, while spending remains sluggish.
Another key factor driving up gold prices is the weakening US dollar, particularly after Federal Reserve Vice Chairman Stanley Fischer hinted that another interest rate hike could impact the US and global economies. Alongside this, gold, silver, and palladium also rose 0.7%. Silver is currently priced at $14.36 per ounce while palladium is at $502.01.
According to Vnexpress.net
| RELATED NEWS |
|---|