KOS shares hit the ceiling price on the morning of November 2nd.
KOS shares continued to rise to their maximum limit during the morning session on November 2nd, extending their recovery after being rescued last weekend.
Opening the trading session on the morning of November 2nd, the stock market continued to be shrouded in red as selling pressure spread across the electronic board.
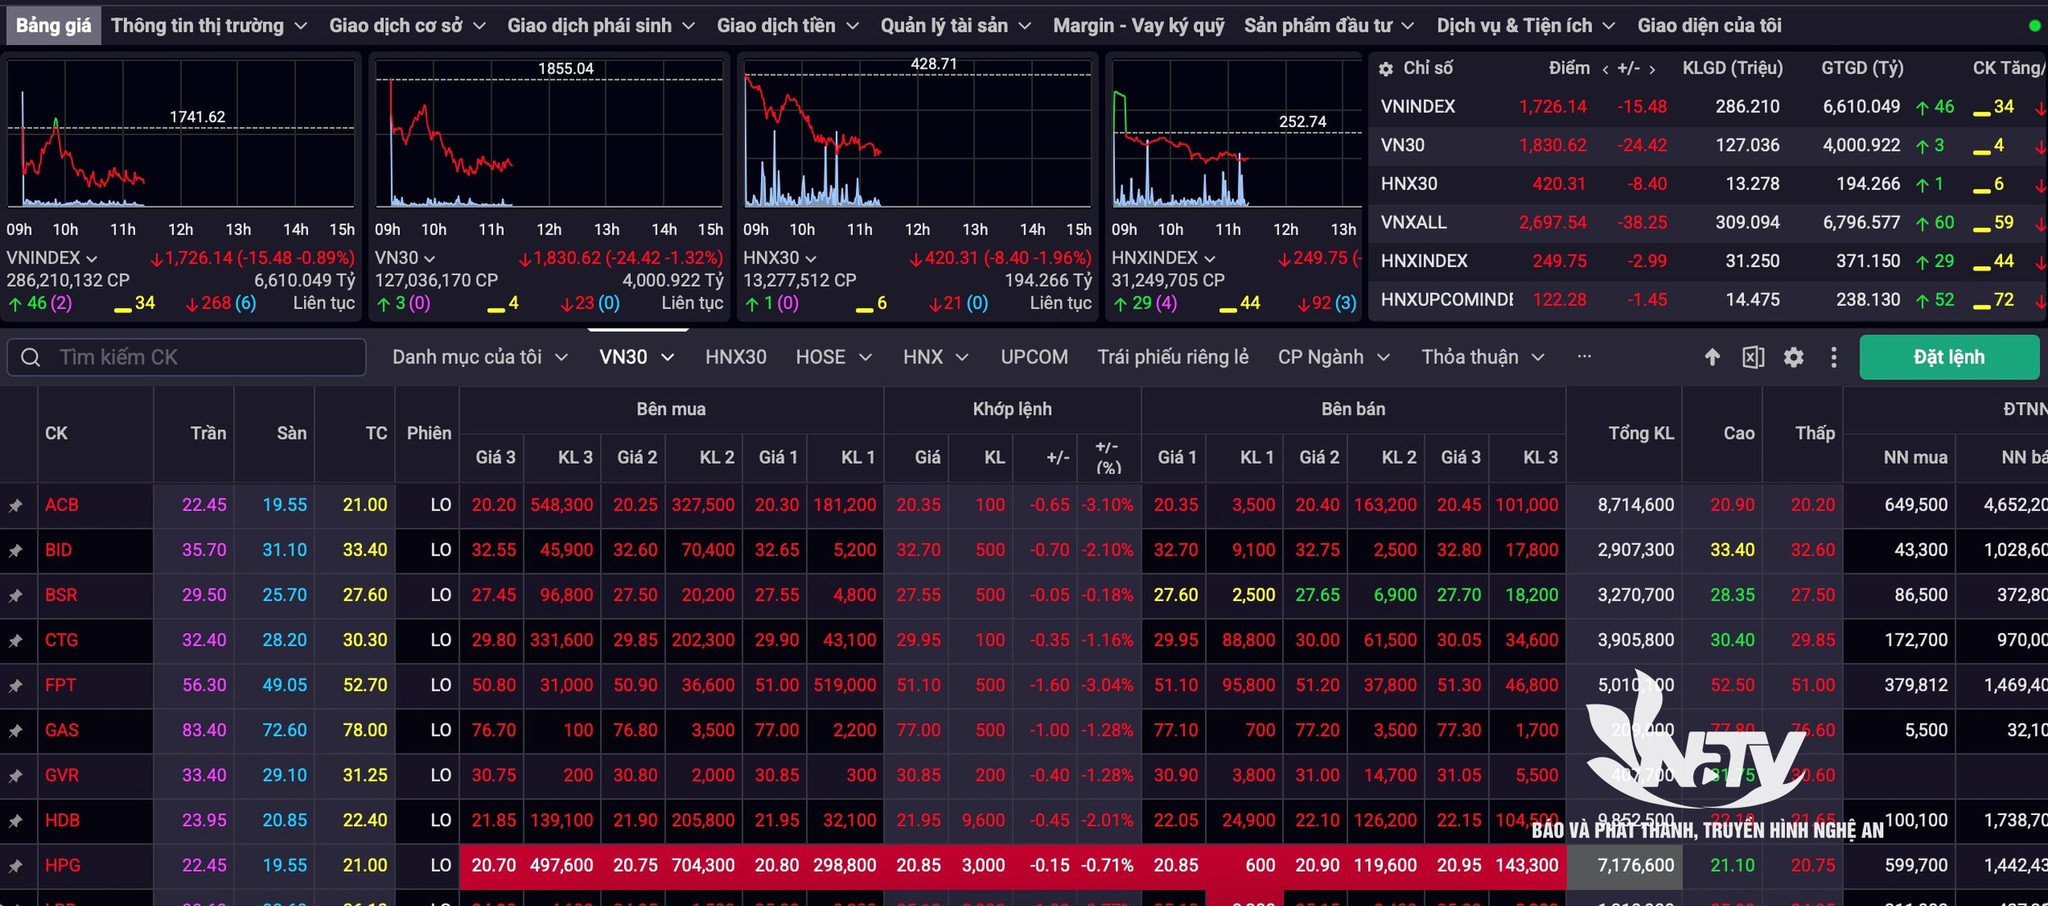
The VN-Index briefly recovered slightly thanks to the positive performance of large-cap stocks, notably VIC and VHM. However, the recovery quickly weakened as demand was not strong enough to improve the overall performance, while most stocks in the VN30 basket remained under downward pressure.
After more than an hour of trading, the number of declining stocks was nearly 2.5 times higher than the number of rising stocks. VIC and VHM also significantly narrowed their gains, no longer strong enough to support the index, causing the VN-Index to fall below the 1,730 point mark.
Significant selling pressure was concentrated in the banking and securities sectors, with red dominating and many stocks falling by 2-3%. This development continued to put pressure on the market amidst cautious investor sentiment.
Among small and medium-sized stocks, KOS maintained its upward trend after a strong recovery at the end of last week. The stock is currently up 6.9%, at 4,340 VND/share, with a trading volume of 6.9 million units, placing it among the most liquid stocks on the market. Notably, the buy order at the ceiling price remains at 3.77 million units, indicating continued positive demand for this stock.
In the banking sector, VCB (-2.66%), HDB (-2.01%), ACB (-3.1%), TCB (-3.7%), VPB (-3.7%), and BID (-2.4%) saw declines. In the stock sector, SSI (-1.81%), VCI (-1.35%), SHS (-1.64%), VND (-2.24%), and TCX (-2.91%) also experienced declines.
The real estate sector showed divergence, with VIC (+1.37%), VHM (+0.79%), VPI (+1.04%), PDR (-3.54%), TCH (-1.27%), CEO (-2.7%), and VRE (-0.42%). The oil and gas sector also saw divergence, with BSR (-0.26%), PLX (-1.32%), PVD (-1.11%), PVS (-2.3%), and OIL (-1.55%).
At the close of trading, the VN-Index fell 15.7 points to 1,725.92 points (-0.9%) compared to the previous session. Similarly, the HNX-Index decreased by 250.02 points (-1.08%), equivalent to 2.72 points, and the UPCoM-Index decreased by 122.23 points (-1.21%), equivalent to 1.5 points.
Market liquidity reached VND 6,971.51 billion, with 305 million shares traded. Across the sector, 49 stocks rose, 270 fell, and 33 dropped to their reference price.
According to experts at Asean Securities Company, the VN-Index is currently in a neutral consolidation phase, with the Spinning Top candlestick at 1,742 points reflecting a balance between supply and demand. Technical indicators such as the RSI at 47 and the MFI weakening at 39 suggest the market lacks clear breakout momentum.
In the base scenario, the index is likely to continue fluctuating within a narrow range around the support zone of 1,740 - 1,750 points before establishing a new trend. Short-term investors should maintain an average stock allocation, avoid chasing rallies, and focus on trading within the 1,740 - 1,770 point range.
At the same time, priority should be given to sectors with their own supporting narratives, such as state divestment, economic development resolutions, and expectations of market upgrade.