An expert's perspective on the supply and demand of capital.
The economy is entering a period of accelerated growth with the goal of achieving double-digit growth, leading to a huge demand for credit. In a context where total outstanding loans sometimes exceed total deposits, solving the problems of interest rates, controlling bad debts, and changing the mindset regarding access to capital are urgent requirements from regulatory agencies, banks, and businesses alike. Reporters from Nghe An Newspaper and Radio & Television had an interview with economic expert, Dr. Nguyen Minh Phong, on these key solutions.
Kim Hoa(Perform) /Present:Hong Toai• September 3, 2026
*****
The economy is entering a period of accelerated growth with the goal of achieving double-digit growth, leading to a huge demand for credit. In a context where total outstanding loans sometimes exceed total deposits, solving the problems of interest rates, controlling bad debts, and changing the mindset regarding access to capital are urgent requirements from regulatory agencies, banks, and businesses alike. Reporters from Nghe An Newspaper and Radio & Television had an interview with economic expert, Dr. Nguyen Minh Phong, on these key solutions.
Dr. Nguyen Minh Phong:As of June this year, the total amount of deposits from individuals and businesses into the banking system reached approximately 17.44 million billion VND, an increase of about 7.1% compared to the end of last year. However, during the same period, outstanding credit has risen to approximately 20.5 million billion VND. This means that total credit demand is exceeding total capital mobilization, and this is the direct cause of upward pressure on deposit interest rates, which in turn leads to higher lending interest rates. To improve this situation, in my opinion, relevant authorities need to focus on implementing four groups of solutions simultaneously.
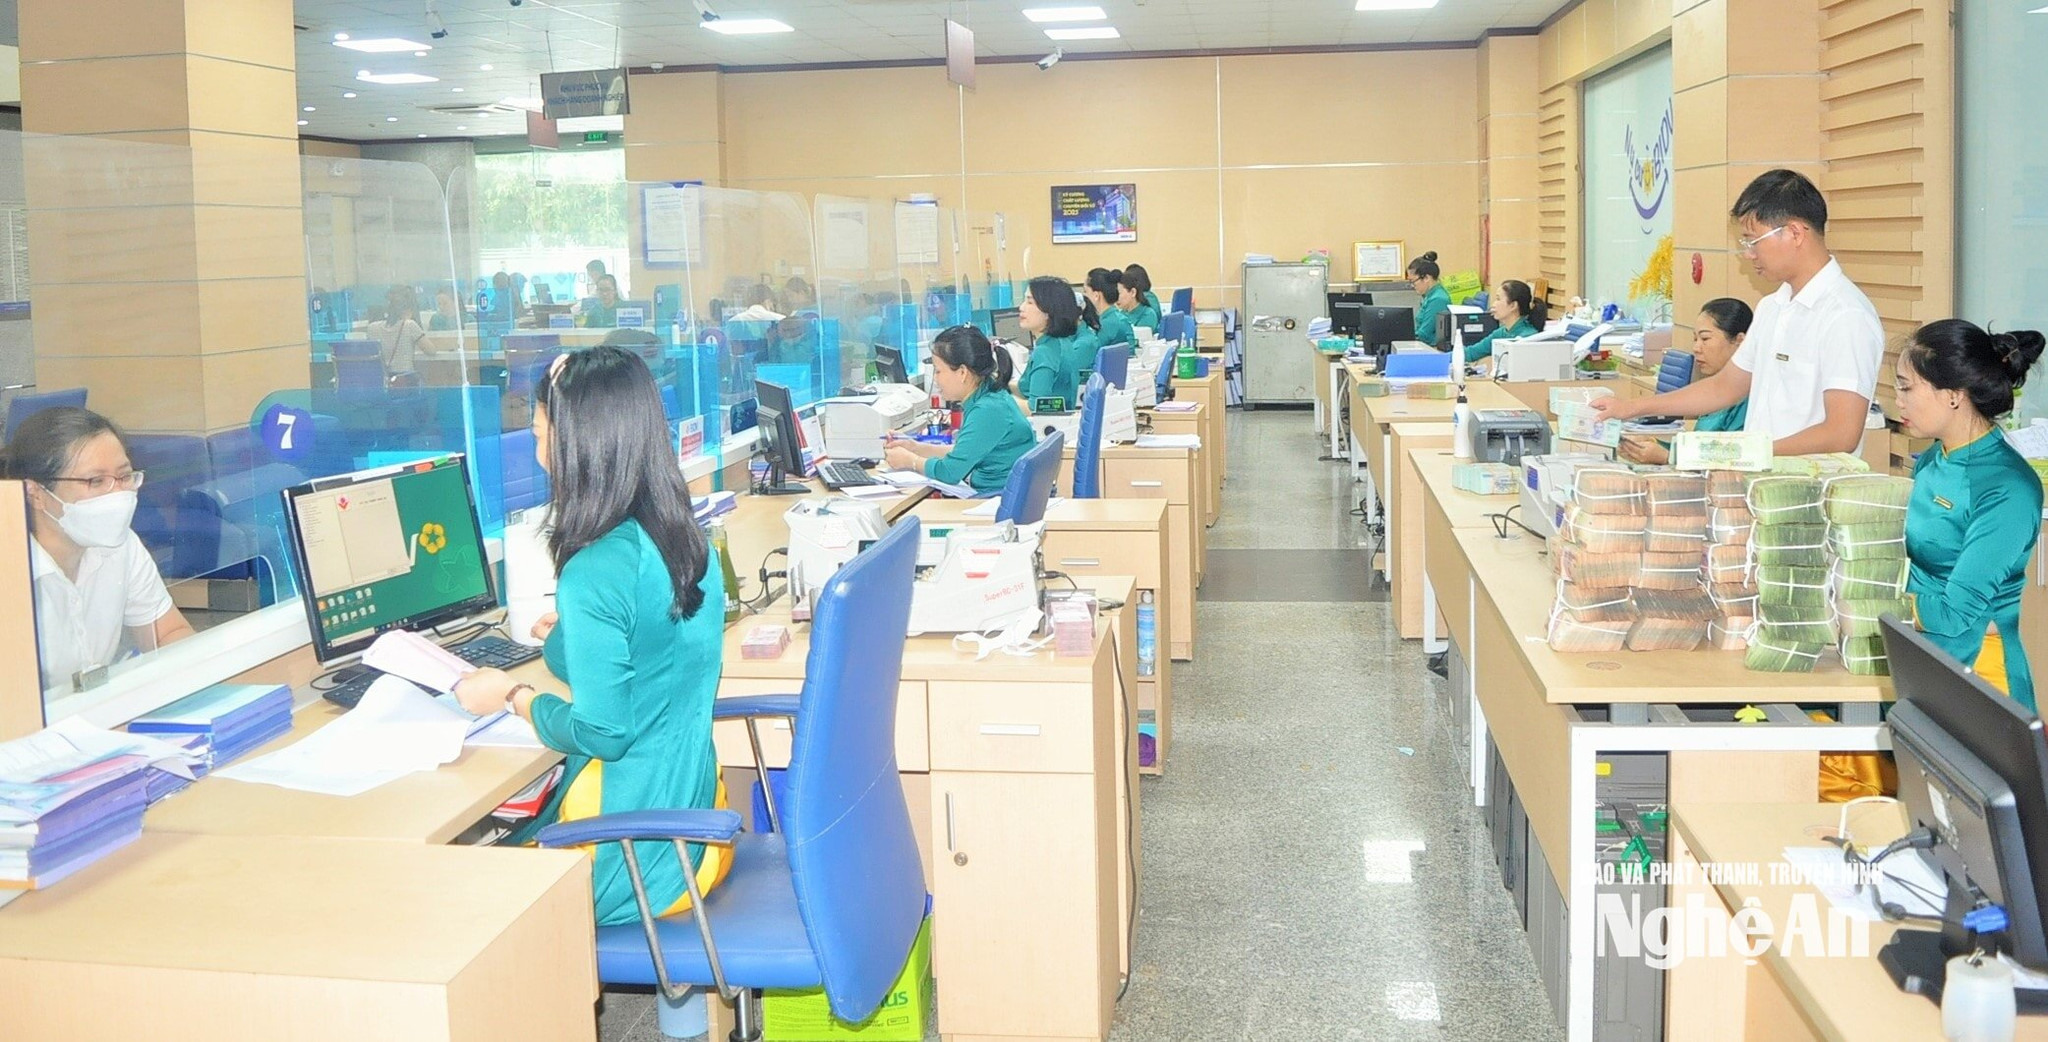
First, it is necessary to reduce the cost of capital for banks, including cutting business expenses, considering reducing the reserve requirement ratio, and not imposing a rigid ceiling on deposit interest rates. At the same time, the State Bank of Vietnam needs to flexibly regulate liquidity and stabilize the money market to limit fierce interest rate wars among credit institutions, especially smaller banks.
Simultaneously, the State Bank of Vietnam should require commercial banks to be more transparent about the components of lending interest rates, while prioritizing credit allocation to businesses with viable business plans and risk-sharing mechanisms. Banks also need to clearly explain their lending structure to the regulatory authority for supervision, ensuring that profit margins do not exceed the market average.
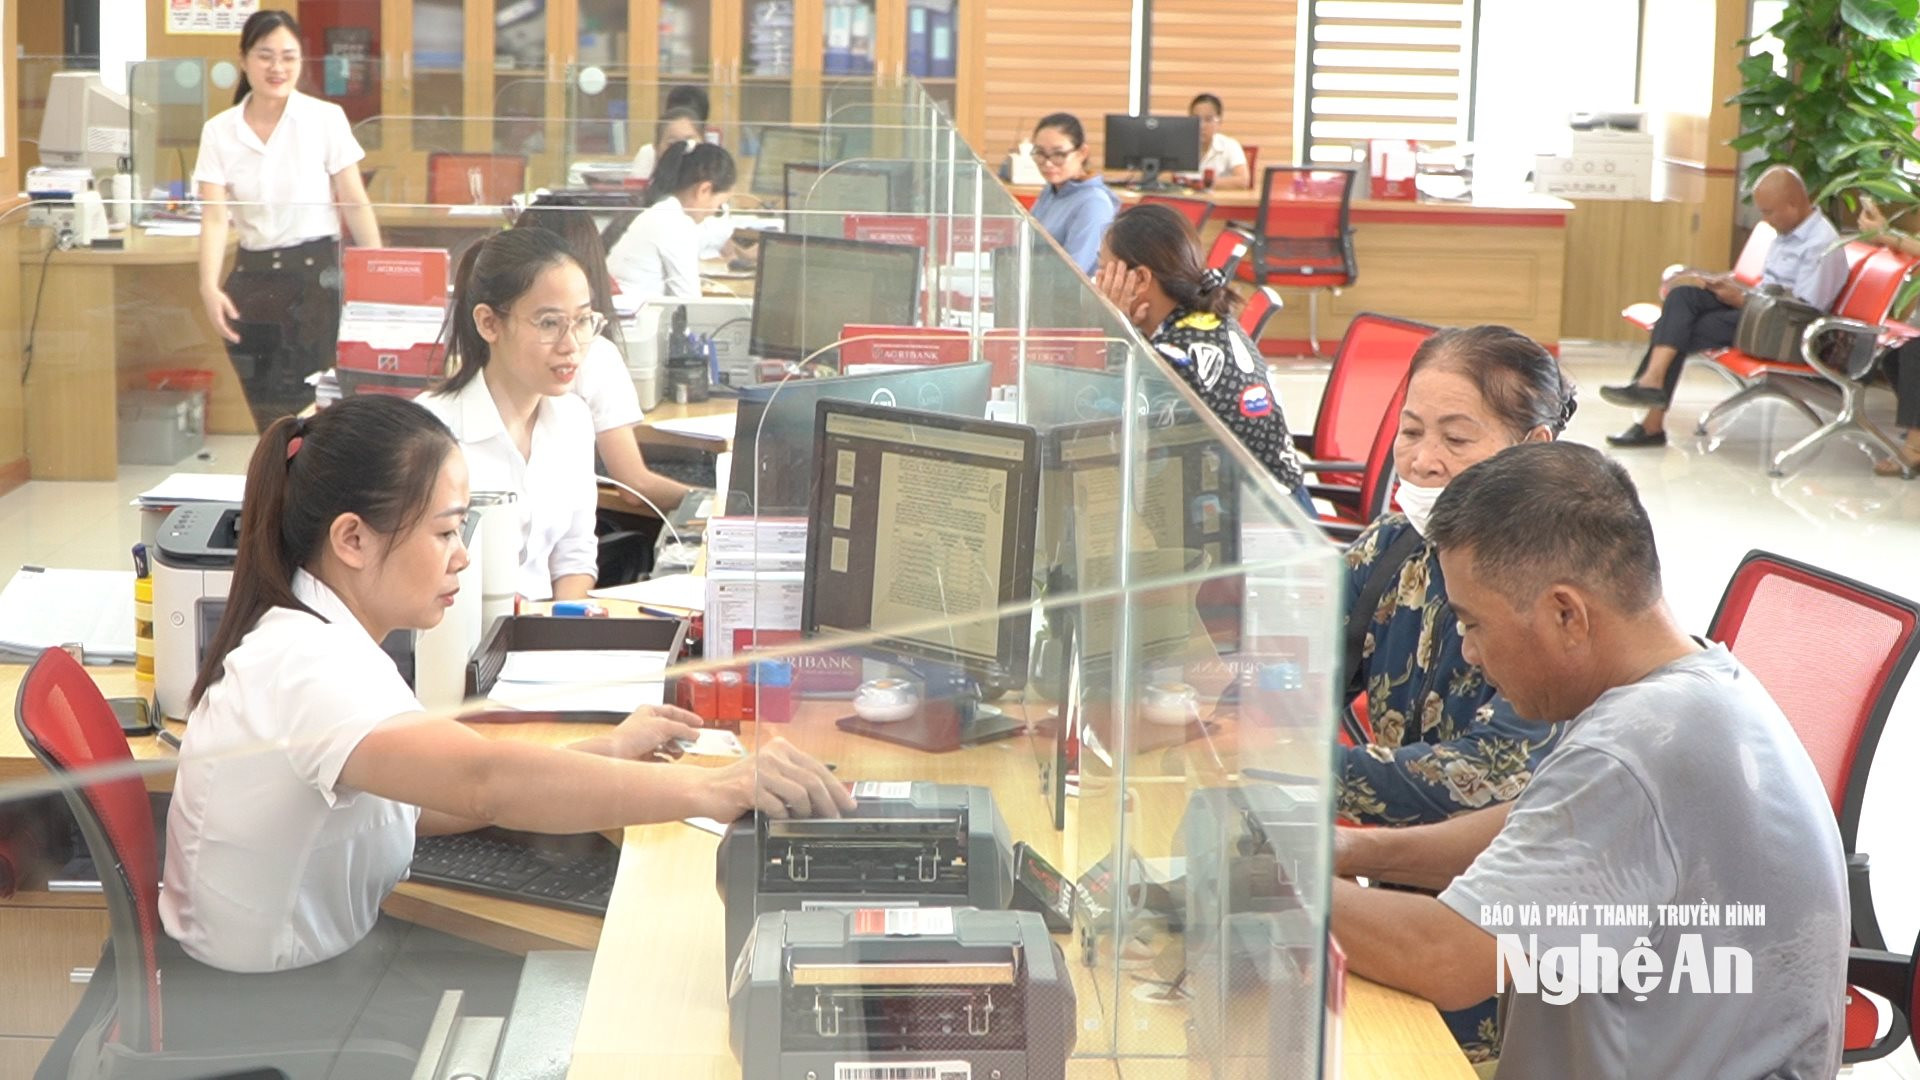
Furthermore, it is necessary to focus on minimizing credit costs and risks from both the business and banking sides, creating more room for credit institutions to proactively reduce their risk premiums.
Besides reducing costs and credit risks from both banks and businesses to create more room for lowering the cost of capital, commercial banks need to proactively increase and diversify service revenue sources beyond traditional deposit and lending activities, reducing their dependence on interest rate spreads. In the coming period, interest rates will continue to face significant pressure from the double-digit growth target, pressure to disburse public investment, imported inflation, and high demand for credit. Therefore, continued close monitoring of the market and encouraging credit institutions to share benefits with customers is extremely necessary.
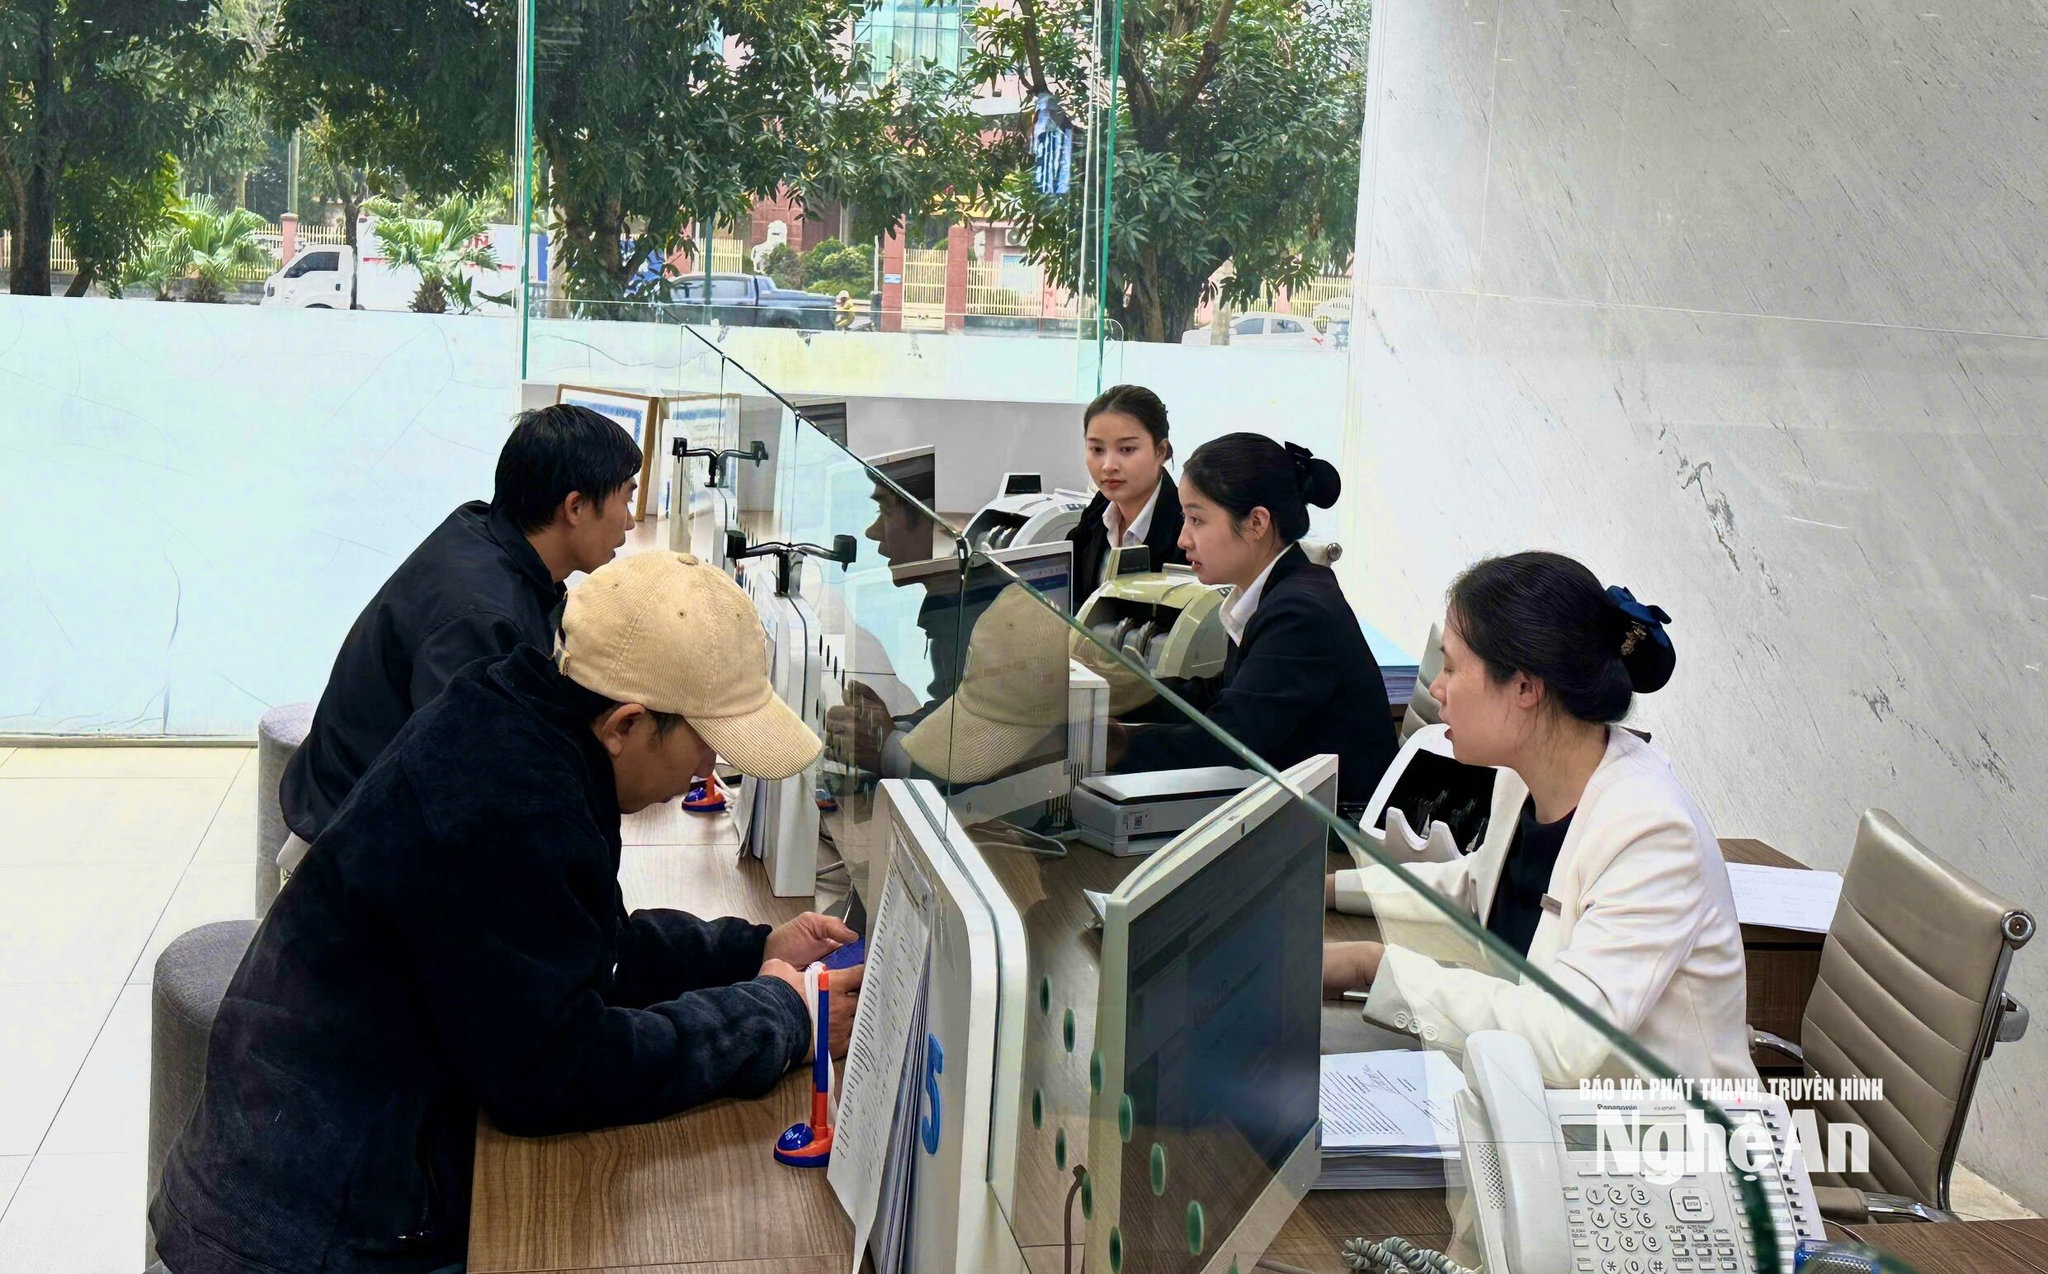
Dr. Nguyen Minh PhongBanking is a unique business sector based on trust and strict governance standards. Balancing the control of bad debts, ensuring system safety, and injecting as much capital as possible into the market is a major challenge, requiring significant effort from both the State Bank of Vietnam and the credit institution system through the following four key solutions.
The key point is that banks need to shift from managing credit growth based on quantity to managing it based on quality, eliminating moral hazard. Banks with strong financial capacity, sound governance, and healthy asset quality should be given more opportunities for proactive growth, while weaker banks need stricter controls to avoid a situation where risks are spread evenly.
Instead of relying rigidly on collateral, customer classification should be based on data and actual credit risk levels. Approval criteria should prioritize cash flow transparency, business plan feasibility, and a good credit history. Customers who meet these criteria should have relaxed collateral requirements to ensure capital flows to the right recipients and in the right direction.
Furthermore, the State Bank of Vietnam needs to create a favorable environment for commercial banks to quickly handle bad debts, helping to unblock capital turnover and reduce overall credit costs. The principle must be upheld: Do not lower safety standards to boost credit growth; instead, lower risk assessment costs through the application of technology, data, and modern credit rating systems.
Finally, a strict reward and penalty mechanism based on credit quality needs to be implemented, applicable to both commercial banks and within each organization. Units with low non-performing loan ratios, effective management, and customers with good credit histories should be given more autonomy in growth limits, while cumbersome procedures should be minimized to enable businesses to seize market opportunities promptly.
PV:In reality, the long-standing barriers related to collateral and disbursement procedures remain a major obstacle preventing many businesses from accessing capital. According to you, what fundamental changes are needed in the methods of providing and accessing capital for both banks and businesses?
Dr. Nguyen Minh PhongThe biggest bottleneck today lies not only in interest rates but also in traditional credit relationships, which are still heavily influenced by the mindset that "collateral is required to obtain a loan." To unlock the flow of capital, both sides need fundamental adjustments in their thinking and working methods.
From the banking perspective, there needs to be a strong shift from lending primarily based on collateral to lending based on cash flow and the actual health of businesses. Businesses with strong cash flow, stable orders, sound financial statements, and a reputable credit history should have their creditworthiness improved, thereby reducing the burden of collateral. In addition, banks need to accelerate the digitalization of appraisal processes to reduce transaction costs, while developing supply chain-based lending models, order-based lending, and accounts receivable lending to leverage the reputation of large partners in the supply chain to support small businesses.
In particular, banks must truly consider businesses as partners, sharing risks and responsibilities according to the principle of harmonious benefits and shared risks. On the business side, they need to actively shift from a mindset of "borrowing with assets" to "borrowing with a business plan." Businesses must strive to improve internal governance, increase financial transparency, and manage all loan cash flows through bank accounts to demonstrate output, orders, and creditworthiness. When actual cash flow is clearly demonstrated, reliance on collateral will naturally be reduced.
PV:Looking ahead to future trends, what are your predictions regarding the movement of idle funds in the economy? Which investment channels have the potential to recover and surge to attract capital?
Dr. Nguyen Minh PhongAmidst an accelerating economy aiming for double-digit growth, coupled with the need to boost public investment and expand credit, bank deposits will continue to be a crucial channel for concentrating idle funds. Deposit interest rates are projected to remain attractive due to the significant supply-demand imbalance. However, there will also be diversification and shifts in financial flows towards investment channels with higher potential for growth.
The first,The stock market will attract capital if listed companies genuinely improve their order volumes, enhance governance quality, and record substantial profit growth.
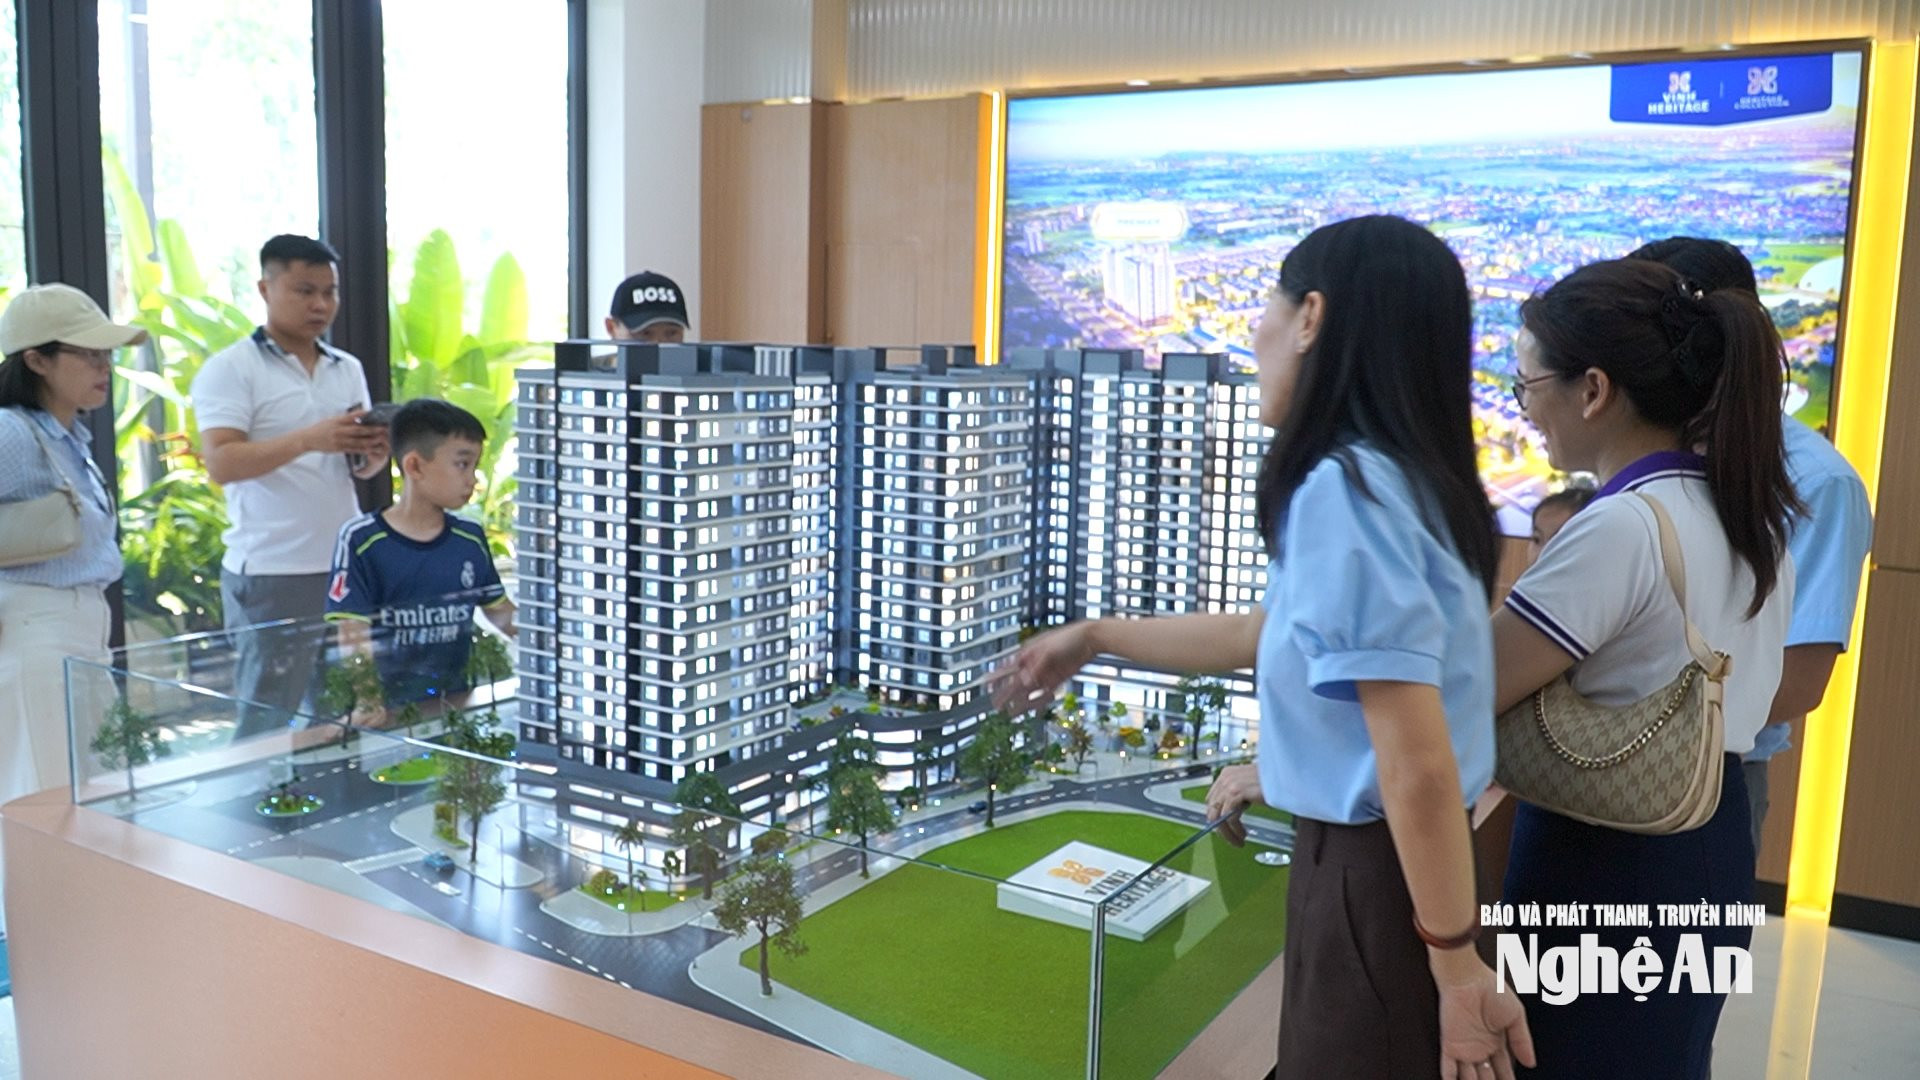
Monday,The real estate market will not experience a simultaneous boom across all segments, but will focus on attracting investment to products that meet real needs, such as social housing, affordable housing, transparent legal frameworks, and integrated amenities.
Tuesday,Gold continues to serve as a safe haven for preserving asset value amidst market volatility and inflationary pressures, particularly suitable for investors with limited capital or business experience.
Overall, this year marks a shift in people's thinking from "purely holding money" to "asset management" aimed at increasing value. Instead of concentrating all capital in a single channel, the popular trend is to diversify portfolios, ensuring both safety and seizing profit opportunities in a volatile market. However, bank savings and gold will remain the primary choices for the majority of people with moderate amounts of idle capital.