Loan sharking: An old scenario, new victims.
Loan sharking, with its enticing promises of high interest rates, has become a dangerous trap for many people in Nghe An province over the past decade, creating a persistent source of suffering for the community. It is noteworthy that despite numerous warnings from the press and media, this tragedy continues to occur, highlighting the urgent need for stricter and more effective management measures.
STRICT MANAGEMENT MEASURES
Over the past five years, Nghe An province has continuously witnessed cases of debt default related to illegal lending, causing much suffering to the community, typical examples include:
The nearly 100 billion VND debt default in Cua Lo and Nghi Loc towns (2017): Sisters Tran Thi Oanh and Tran Thi Xuan raised capital from local people with high interest rates.
The Hung Thao gold shop incident in Con Cuong town (2020): The Hung Thao gold shop in Con Cuong town declared bankruptcy, with the amount involved reaching tens of billions of VND. Hundreds of people were affected after depositing money hoping to earn high interest rates.
The incident in Quynh Long commune, Quynh Luu district (October 18, 2024): Hundreds of people gathered in front of the house of Ms. Bui Thi Nhung, one of the major fundraising figures in the area, with the promise of high interest rates.
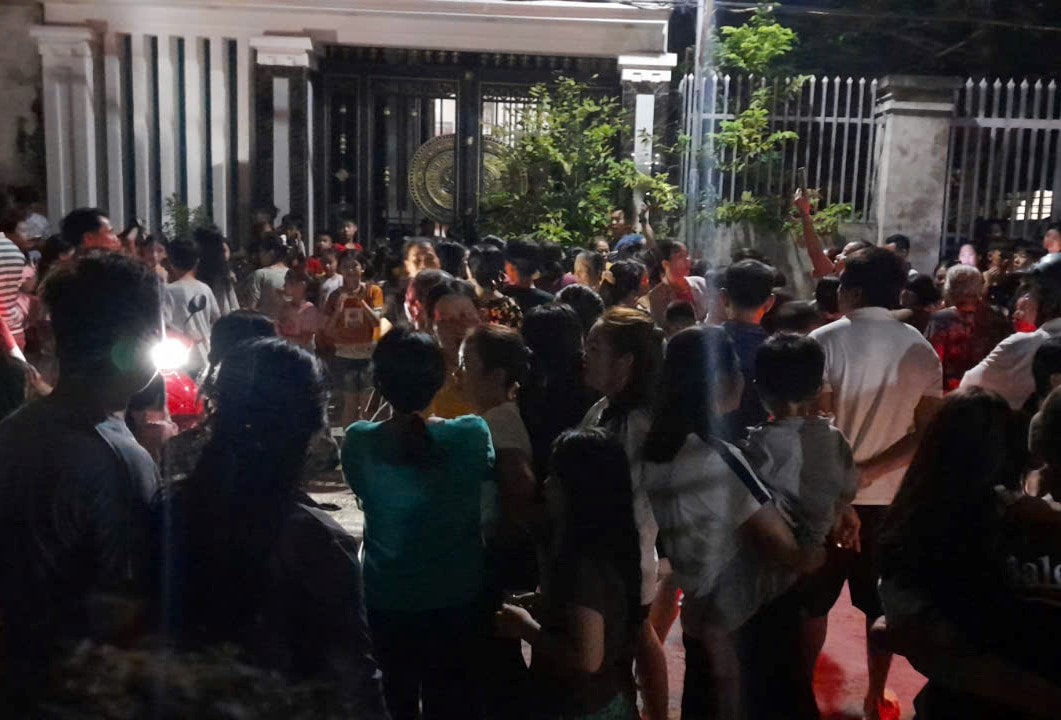
These cases clearly illustrate the terrible consequences of illegal lending. Although they occurred at different times, they all share a common scenario: raising capital from people with promises of high interest rates, then declaring bankruptcy when unable to maintain the funds to pay the interest.
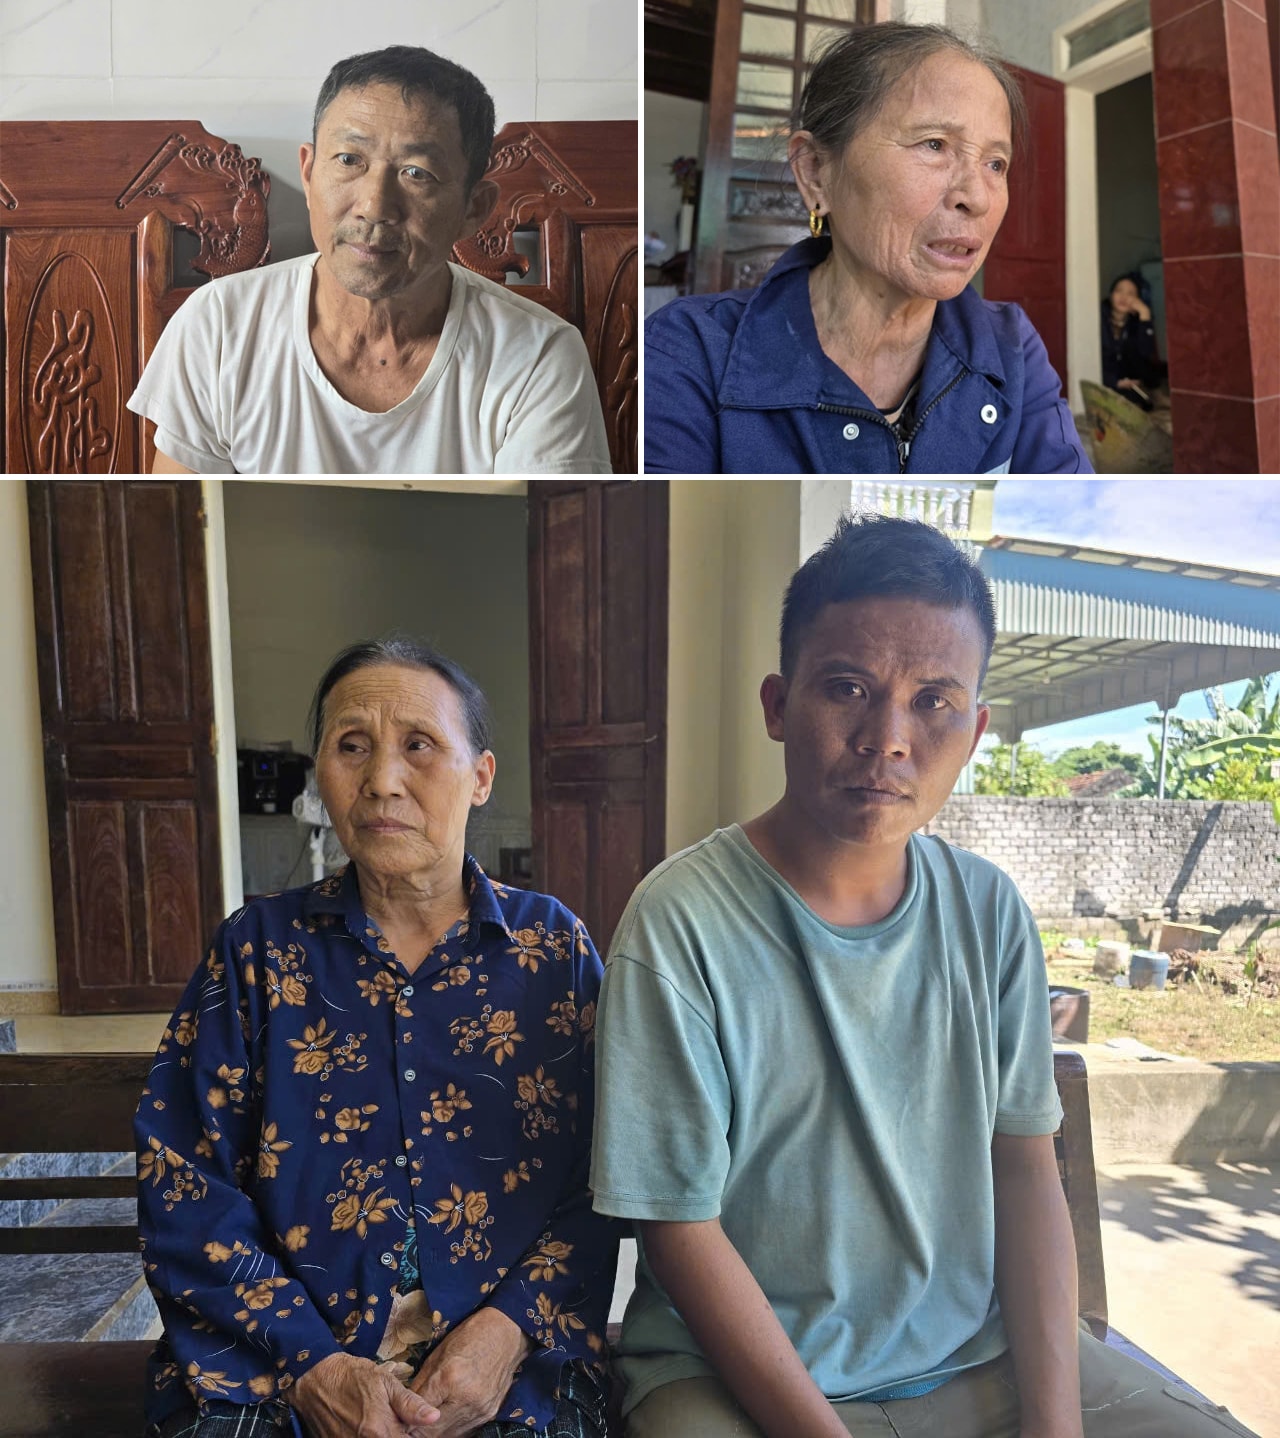
Loan sharking not only causes financial losses but also leaves deep emotional scars on the entire community. Lenders, from households to individuals, face the prospect of losing all their assets, leading to severe psychological distress. Many have lost their life savings, even mortgaging assets like land titles and borrowing more money to invest in these schemes.
The consequences extend beyond financial loss; it also shatters family and friendships due to financial stress. Many people are forced to leave their hometowns to find work and rebuild their lives. Others find themselves in a desperate situation, living in fear and pressure from loan sharks demanding repayment. This has plunged many families into destitution and created social instability.
LEGAL LOOPHOLES THAT NEED TO BE ADDRESSED
Debt defaults related to illegal lending in Nghe An not only reflect a lack of financial management awareness among the people but also highlight legal loopholes in controlling underground lending activities. Many fraudsters exploit people's trust, organizing unofficial lending operations with interest rates far exceeding legal regulations.
Article 468 of the 2015 Civil Code stipulates that interest rates on loans must not exceed 20% per year of the loan amount, unless otherwise specified by law. Lending by illegal lenders at interest rates higher than this is a violation of the law.
According to the 2015 Penal Code (amended and supplemented in 2017), Article 201 stipulates that the crime of "usurious lending in civil transactions" can be punishable by imprisonment from 6 months to 3 years if the illicit profit is 30 million VND or more.
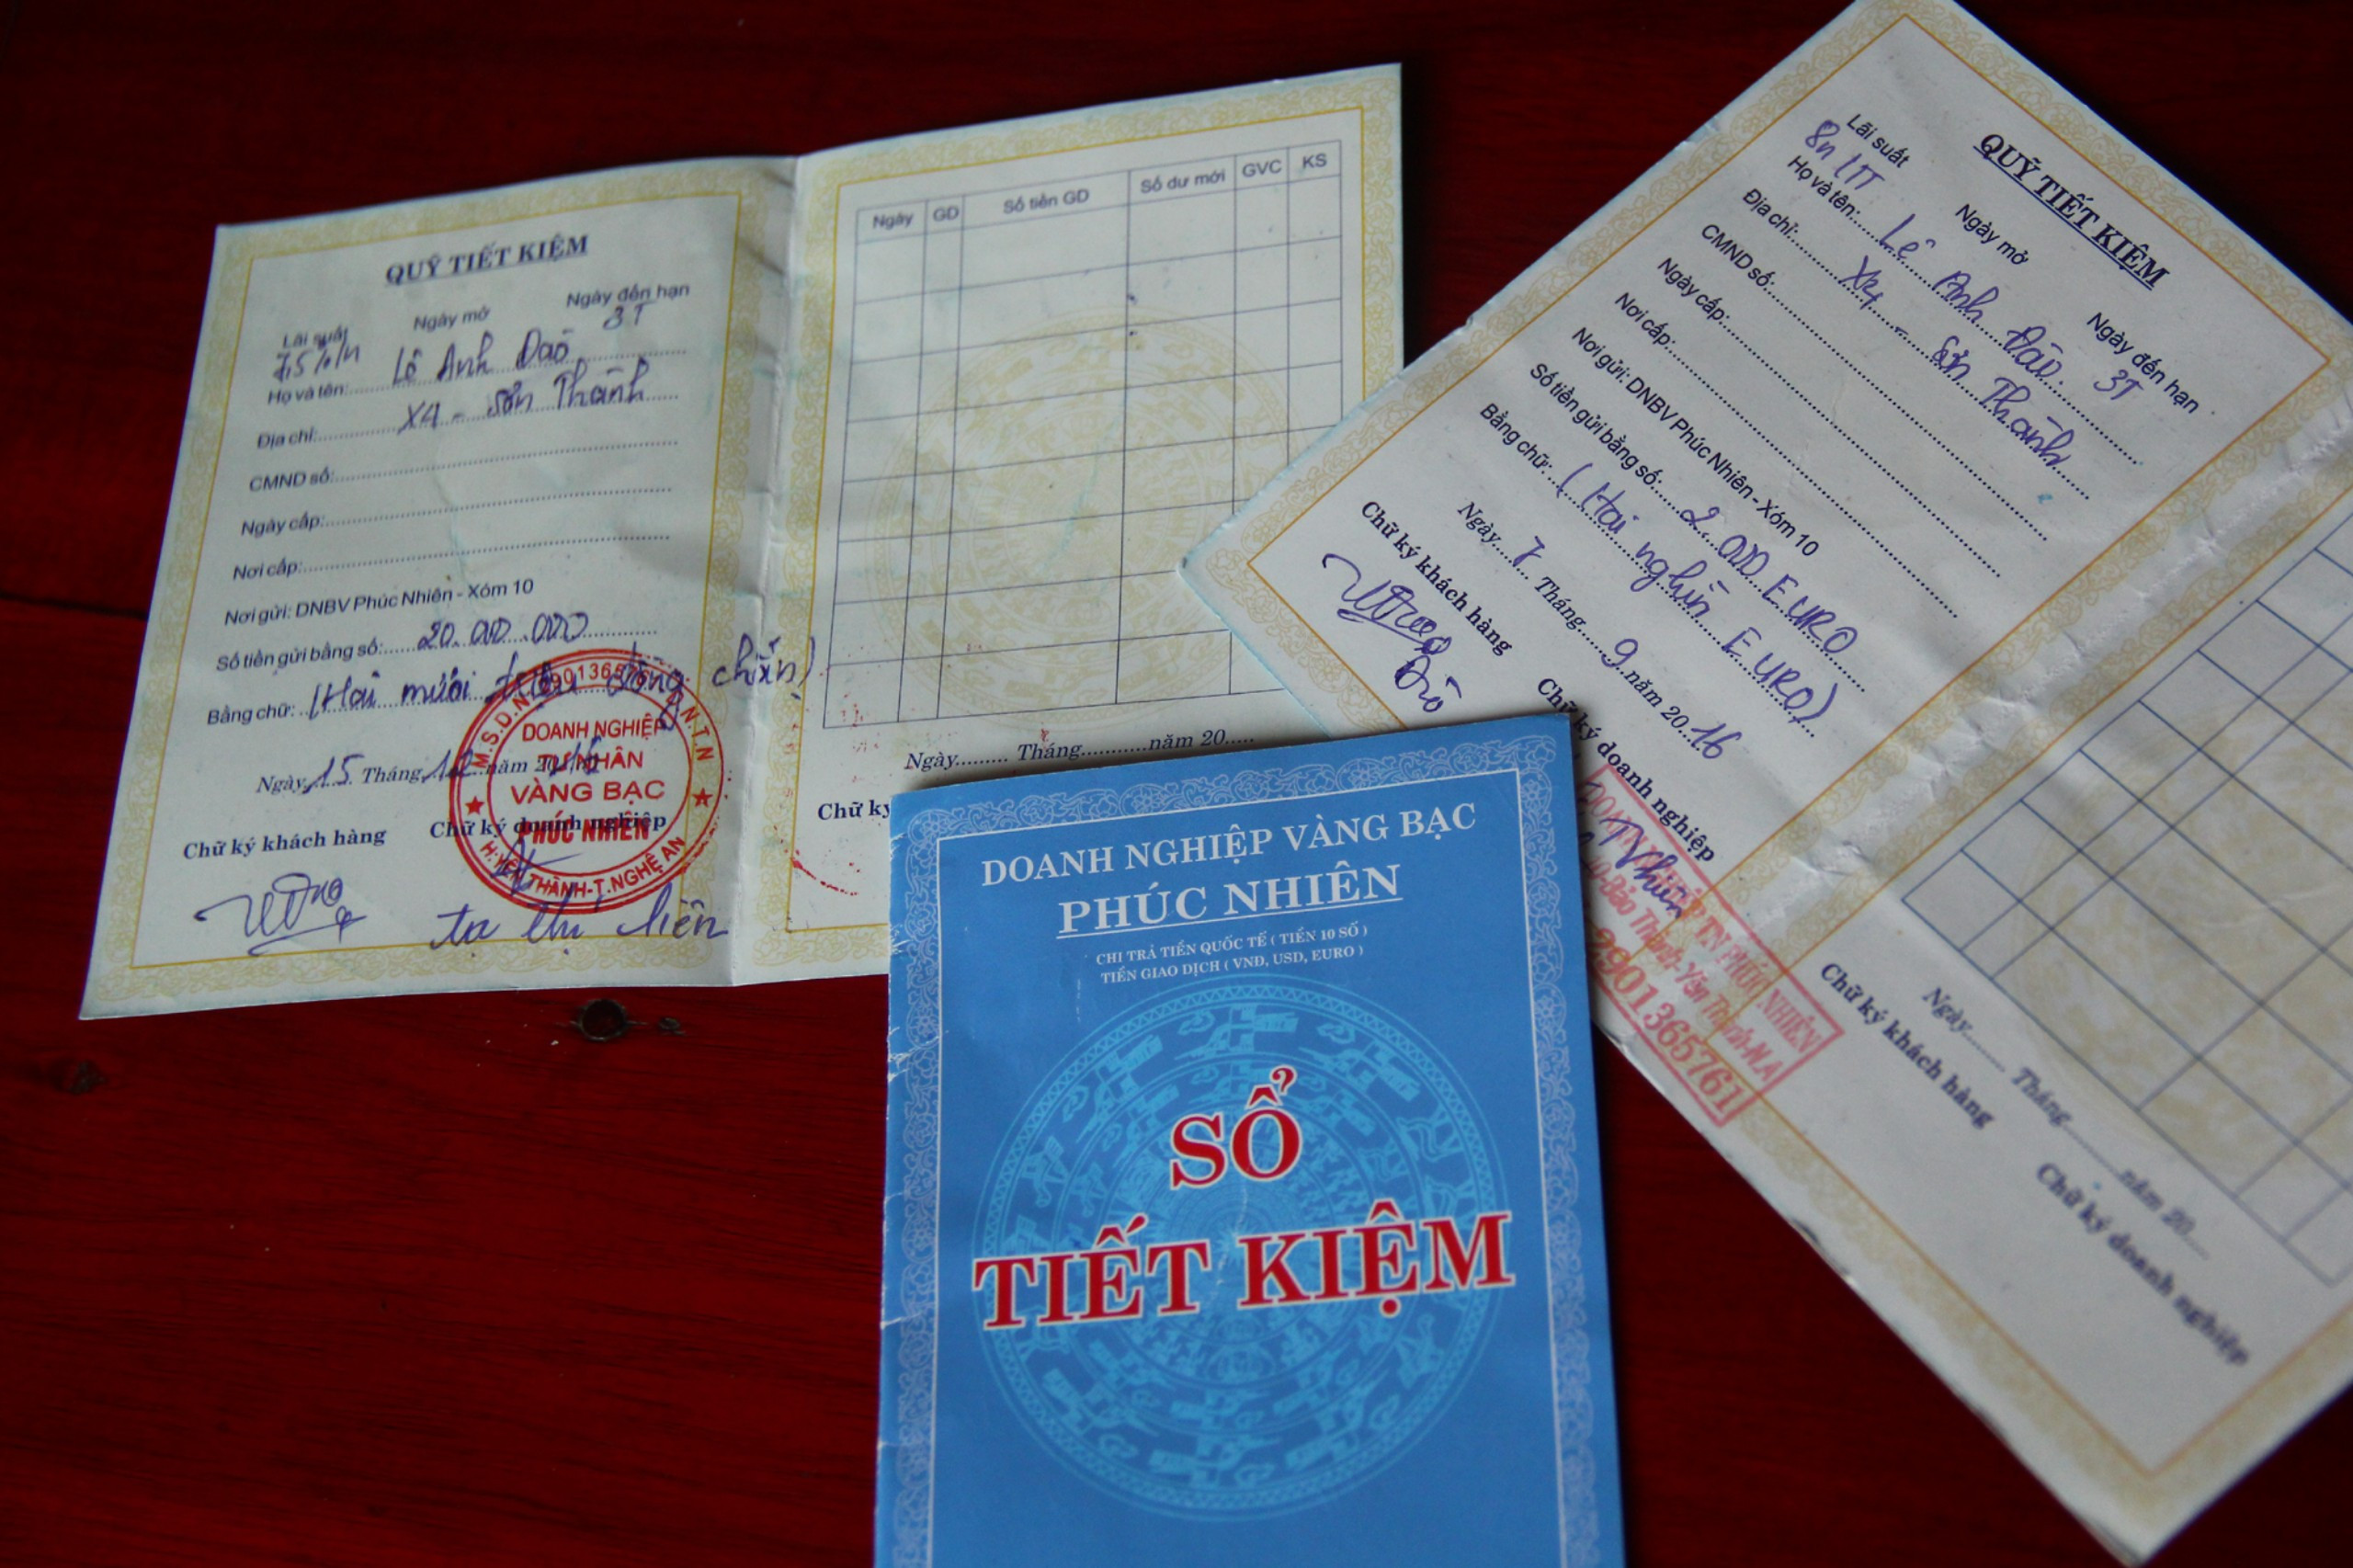
Nghị định 144/2021/NĐ-CP: Quy định xử phạt hành chính đối với hành vi vi phạm như cho vay nặng lãi, tổ chức huy động vốn không phép, với mức phạt từ 20-100 triệu đồng.
Các hoạt động tín dụng ngầm thường diễn ra bí mật, khó phát hiện và thường núp bóng dưới các giao dịch hợp pháp như hợp đồng mua bán, cho thuê tài sản. Cùng với đó, nhiều người dân thiếu hiểu biết về pháp luật, bị thu hút bởi lãi suất cao mà không nhận thức rõ các rủi ro tiềm ẩn. Điều này tạo cơ hội cho tín dụng đen phát triển mạnh, gây ra nhiều hậu quả nghiêm trọng cho xã hội, như nợ nần, mất tài sản, và bất ổn kinh tế trong cộng đồng.
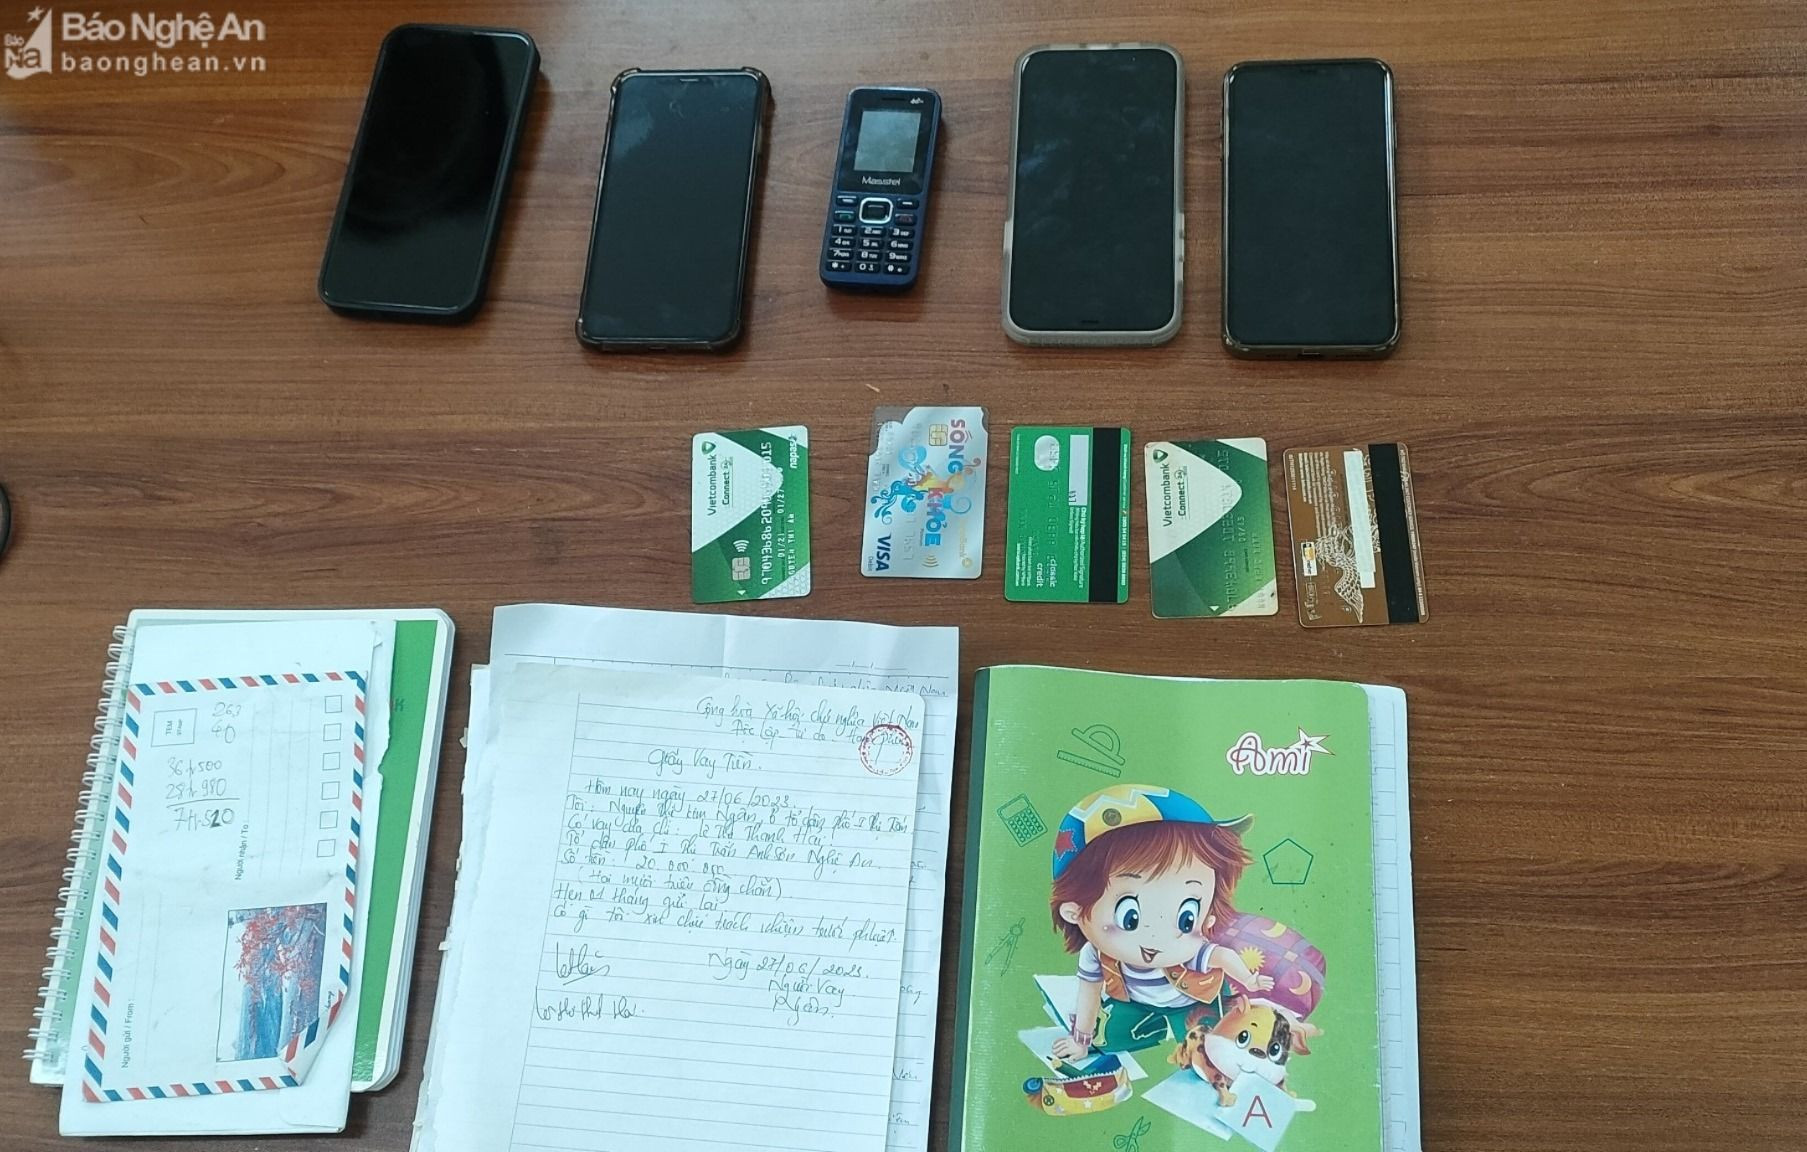
Việc thiếu sự phối hợp chặt chẽ giữa các cơ quan chức năng cũng khiến quá trình điều tra, xử lý trở nên chậm trễ và phức tạp. Các đối tượng hoạt động tín dụng đen thường sử dụng những thủ đoạn tinh vi như lấy tiền lãi trước (tầm 10 ngày), giữ giấy tờ tùy thân của người vay, khiến cơ quan chức năng khó có thể chứng minh hành vi cho vay nặng lãi.
CẦN SỰ PHỐI HỢP TỪ CHÍNH QUYỀN VÀ CÁC TỔ CHỨC TÀI CHÍNH
1. Giám sát và xử lý vi phạm: Chính quyền các cấp phải nâng cao hiệu quả giám sát, đảm bảo rằng, các hành vi cho vay nặng lãi được phát hiện và xử lý kịp thời. Điều này đòi hỏi sự phối hợp chặt chẽ giữa các cơ quan chức năng như công an, cơ quan tư pháp và chính quyền địa phương, nhằm thực hiện các biện pháp ngăn chặn từ gốc. Việc này không chỉ bảo vệ người dân khỏi những rủi ro tài chính mà còn răn đe các đối tượng cho vay nặng lãi, giảm bớt sự phát triển của tín dụng đen.
2. Tuyên truyền trên các kênh truyền thông: Đây là yếu tố then chốt giúp người dân nhận thức rõ về những rủi ro của tín dụng đen. Qua đó, chính quyền cần tổ chức các buổi hội thảo, chương trình truyền thông để cung cấp thông tin về các hình thức cho vay hợp pháp, những dấu hiệu nhận biết lừa đảo và cách bảo vệ quyền lợi của bản thân. Việc này giúp người dân, đặc biệt ở vùng nông thôn, có cái nhìn rõ ràng hơn, từ đó hạn chế bị lừa đảo và tìm kiếm những giải pháp vay vốn an toàn hơn.
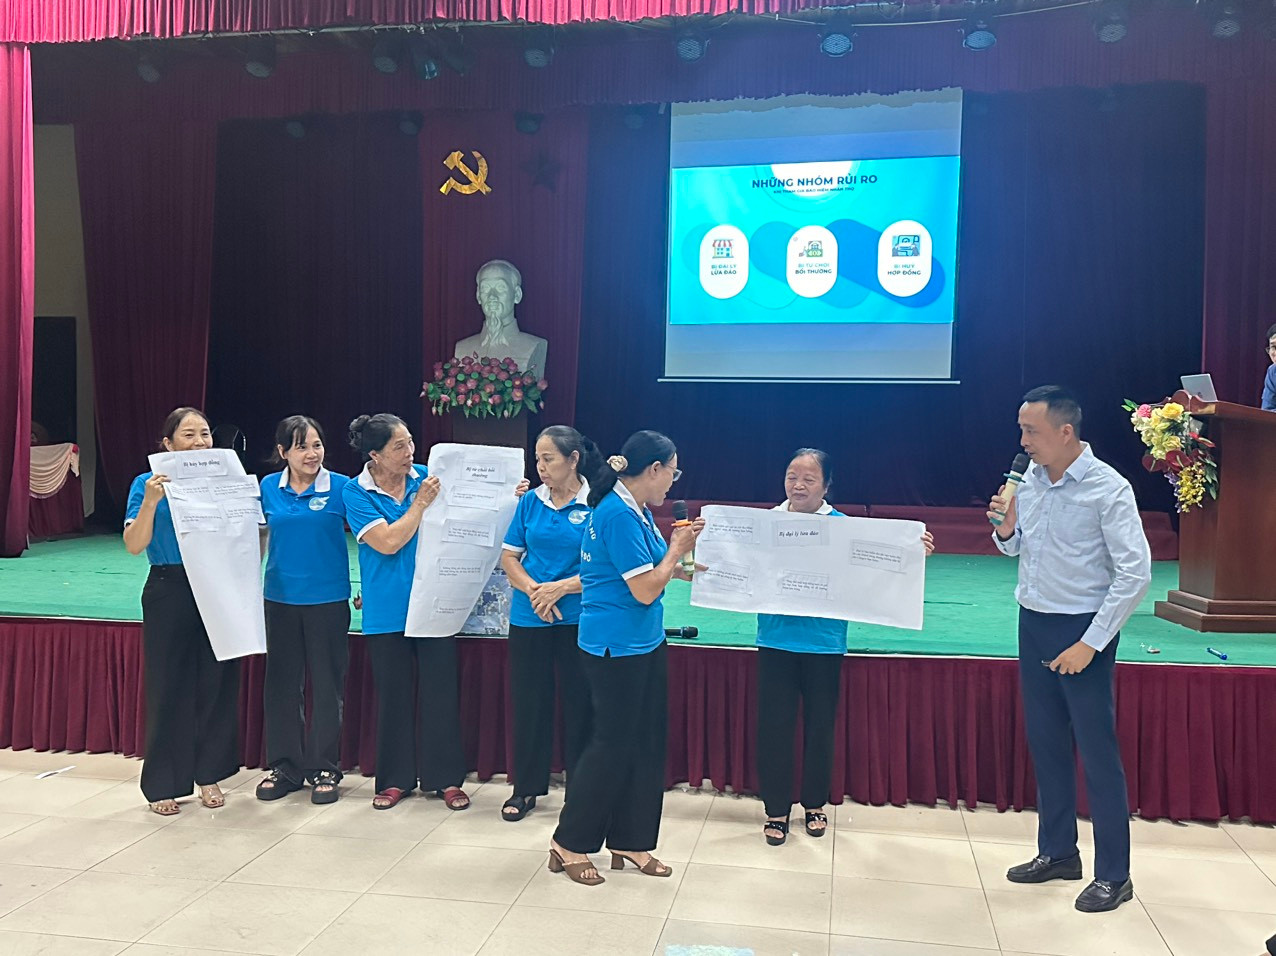
3. Expanding formal credit channels:Formal financial institutions need to fulfill their role in providing safe credit products with reasonable interest rates, while minimizing complicated procedures to make them easily accessible to the public. Expanding lending channels from banks or social credit funds will help people avoid resorting to illegal lending when facing financial difficulties. This not only helps people steer clear of illegal lending but also creates long-term economic stability for the community.
4. Develop financial support programs for rural and mountainous areas:For areas with limited access to financial services, bringing loan support programs closer to the people is crucial. Banks and financial institutions should cooperate with local authorities to implement microcredit programs, enabling people to borrow small amounts of money at preferential interest rates. This not only creates opportunities for sustainable economic development but also reduces the risk of people being drawn into illegal lending schemes.
Cases of defaults due to predatory lending are not merely financial issues, but also lessons about the need for stricter control and increased public awareness of financial risks. By implementing coordinated legal measures and support from financial institutions, we aim to build a healthier economic environment, preventing tragedies like predatory lending from recurring.